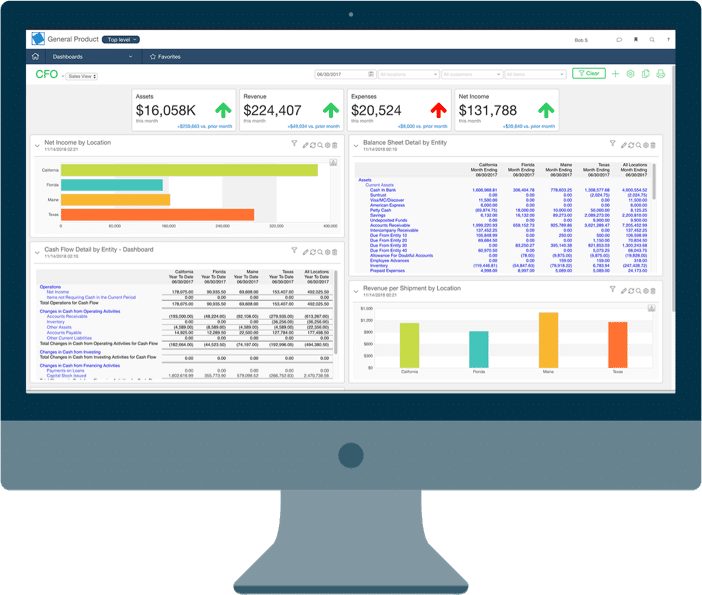
AssetAccountant is sophisticated fixed asset software that handles all your fixed asset depreciation and leasing needs.
Australia and the Australian Taxation Office (ATO) have unique rules around taxes and depreciation for vehicles. AssetAccountant navigates all of these rules automatically.
ATO Definition, What is a "Luxury Car"?
The ATO defines a luxury car differently from most people’s everyday understanding.
Most of us think of luxury cars as high-end German performance vehicles or premium 4WDs. However, for tax and depreciation purposes, the definition focuses on price thresholds rather than brand or style.
The ATO defines a luxury car as any motor vehicle with a purchase price above the luxury car threshold. This threshold is indexed yearly. At the time of writing, it sits at $68,740 — or $77,565 for fuel-efficient cars (effective from July 2020).
As a result, the ATO’s definition can include many mainstream vehicles — such as sedans, station wagons, SUVs, and 4WDs.
AssetAccountant – saving you from spreadsheets since 2019
Luxury Car Tax
The ATO applies a Luxury Car Tax (LCT) when businesses sell or import luxury cars into Australia. The LCT rate is 33% and applies to the GST-inclusive value above the $68,740 threshold.
Businesses that sell or import luxury cars pay this tax. Individuals who import luxury cars also pay it.
For example, a $100,000 BMW imported into Australia exceeds the $68,740 threshold by $31,260. At 33%, the importer pays $10,316 in Luxury Car Tax to the ATO.
What is the depreciation allowance or "Car Limit" as the ATO refers to it?
The ATO sets a maximum depreciation allowance for vehicles — known as the Car Limit. From July 2020, this limit is $59,136. From July 2021, it increased to $60,733.
This limit applies to passenger vehicles designed to carry fewer than nine passengers and a load of less than one tonne.
For example, if your business buys a vehicle for $100,000, you can only depreciate $59,136 of that amount — regardless of any trade-in you received.
Understanding the one tonne limit
The one tonne limit refers to the vehicle’s payload capacity — the maximum load it can carry. To calculate payload capacity, subtract the basic kerb weight from the Gross Vehicle Mass (GVM).
The manufacturer always notes the GVM on the compliance plate. The basic kerb weight includes a full tank of fuel, oil, and coolant, plus the spare wheel, tools, and factory-installed options. It does not include passengers, goods, or accessories added after original specifications.
Which vehicles are exempt from the Car Limit?
Some vehicles fall outside the Car Limit entirely. Businesses can depreciate the full purchase cost of:
- Any vehicle with a payload greater than one tonne
- Any vehicle designed to carry nine or more passengers
The Car Limit does not apply to motorcycles or vehicles fitted out for use by people living with a disability.
Taxable use
If you use a vehicle for both business and private purposes, you can only claim depreciation on the business portion. This rule applies to all depreciable assets, not just vehicles.
Furthermore, if the Car Limit applies to your vehicle, the depreciation deduction is limited to the business portion of that limit.
For example, if you use your vehicle for 80% business purposes and it cost more than $59,136, your maximum depreciation claim is 80% of $59,136 — which equals $47,308.
Fixed asset depreciation and leasing – taken seriously
We undertake detailed modelling of fixed asset depreciation and lease calculation rules for both accounting and tax.
We monitor changes to tax rulings and accounting standards like IFRS and US GAAP so you don’t have to.
And, of course, we are ISO27001 certified.
Ask our team anything
Watch your inbox for an email from support@asset.accountant!
We'll use these details to respond to your enquiry and to send you occasional information about AssetAccountant. We never sell your data or share it for others' marketing. Your data is processed in Australia. Unsubscribe any time via any email or privacy@asset.accountant. See our Privacy Policy.
GST consideration for depreciable amount and the Car Limit
GST treatment affects how you calculate the depreciable amount:
- If you are registered for GST and can claim the full GST credit, exclude the GST amount from your depreciation calculation.
- If you are not registered for GST, include the GST amount in your depreciation calculation.
What About the Instant Asset Write Off?
Vehicles can take advantage of the Backing Business Investment Instant Asset Write-Off rules. However, the Car Limit still applies. You cannot write off more than the Car Limit for any eligible vehicle.
If your business qualifies for the instant asset write-off but you prefer not to claim the full amount, you do not have to. The choice remains yours.